
Despite global uncertainties, Vietnam’s industrial real estate market continues to attract strong investor interest, driven by robust foreign direct investment (FDI), expanding manufacturing activities, and ongoing supply chain diversification.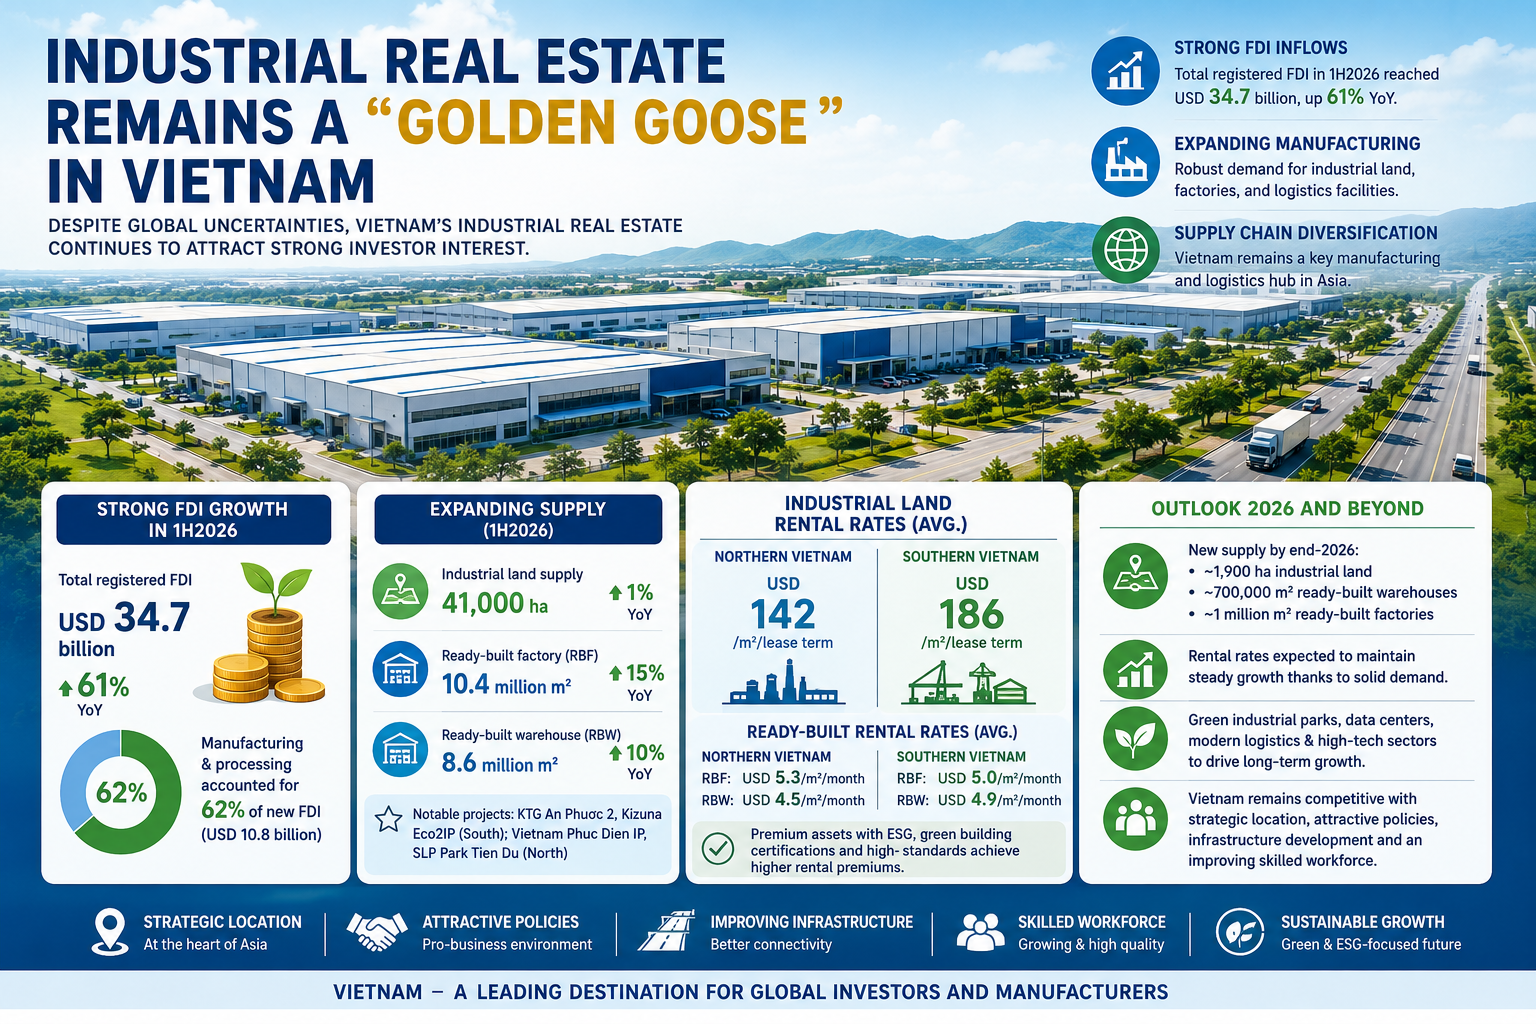
Industrial Real Estate: The Gold Mine of Vietnam’s Property Market
Vietnam’s industrial real estate sector continues to benefit from strong foreign investment inflows. During the first six months of 2026, total registered FDI reached USD 34.7 billion, representing a 61% increase year-over-year. The manufacturing and processing sector accounted for 62% of newly registered FDI, equivalent to USD 10.8 billion.
Amid geopolitical uncertainties and evolving global trade policies, Vietnam has maintained its position as a key manufacturing and logistics hub in Asia. This provides a solid foundation for continued demand for industrial land, ready-built factories, and modern logistics assets in major production centers.
Notably, investors continue to prioritize income-generating assets such as ready-built factories and warehouses, reflecting the sustained demand for high-quality industrial properties.
Supply Continues to Expand While Demand Remains Strong
According to data from JLL, during the first half of 2026, total industrial land supply across Vietnam’s key northern and southern markets reached nearly 41,000 hectares, up 1% year-over-year.
Meanwhile:
- Ready-built factory (RBF) supply reached approximately 10.4 million square meters, increasing by 15%.
- Ready-built warehouse (RBW) supply totaled around 8.6 million square meters, up 10% compared to the same period last year.
Notable new developments include:
Southern Vietnam
- KTG Industrial An Phước 2
- Kizuna Eco2IP at the expanded Tân Kim Industrial Park
Northern Vietnam
- Vietnam Phúc Điền Industrial Park
- SLP Park Tiên Du
Market absorption remained healthy, with hundreds of hectares of industrial land transacted, alongside approximately 350,000 square meters of ready-built factories and 450,000 square meters of ready-built warehouses leased during the first half of the year.
Most demand came from existing tenants expanding their operations.
Manufacturing and Logistics Continue to Drive Demand
Tenant demand varies by region:
Southern Vietnam
Industrial properties are primarily occupied by businesses in:
- Textiles and garments
- Mechanical engineering
- Food processing
- Fast-moving consumer goods (FMCG)
Northern Vietnam
Industrial facilities mainly serve:
- Electronics manufacturing
- Technology companies
- High-tech industries
Meanwhile, logistics providers and e-commerce companies continue to sustain strong demand for warehouse and distribution facilities.
Expansion Toward Emerging Industrial Markets
A growing number of companies are exploring opportunities beyond traditional industrial hubs such as:
- Bắc Ninh
- Hải Phòng
- Bình Dương
- Đồng Nai
Emerging provinces are attracting investors due to:
- Larger land availability
- Competitive costs
- Improving infrastructure connectivity
- Greater long-term development potential
This trend is expanding Vietnam’s industrial map and creating new growth opportunities for secondary markets.
Industrial Land Rental Prices Continue to Rise
Industrial land rental rates continue to increase as the supply of high-quality land in strategic locations becomes more limited.
As of the end of the first half of 2026:
Average Net Asking Rent
Northern Vietnam
- USD 142 per square meter per lease term
Southern Vietnam
- USD 186 per square meter per lease term
Industrial parks located near international seaports, airports, and major expressways continue to command premium rental rates due to strong demand and high occupancy levels.
Conversely, emerging markets with abundant land supply are offering more options to tenants, helping ease short-term pricing pressure.
Ready-Built Factory and Warehouse Rental Rates Remain Stable
Northern Vietnam
Ready-Built Factories
- USD 5.3 per square meter per month
Ready-Built Warehouses
- USD 4.5 per square meter per month
Southern Vietnam
Ready-Built Factories
- USD 5.0 per square meter per month
Ready-Built Warehouses
- USD 4.9 per square meter per month
Rental rates are expected to remain stable in the near term. However, premium assets that meet advanced fire safety standards, ESG requirements, energy management criteria, and green building certifications continue to achieve higher rental premiums than the broader market.
Green Industrial Parks Expected to Lead Future Growth
JLL experts expect Vietnam’s industrial real estate market to maintain positive momentum over the next 12–24 months, supported by:
- High-quality FDI inflows
- Regional manufacturing relocation
- Major infrastructure projects under development nationwide
By the end of 2026, Vietnam is expected to add:
- Approximately 1,900 hectares of industrial land
- Nearly 700,000 square meters of ready-built warehouses
- Around 1 million square meters of ready-built factories
Despite the significant increase in supply, rental rates are projected to continue growing steadily due to sustained demand.
ESG and High-Tech Industries Become Key Drivers
According to Will Tran, Head of Industrial and Office Leasing at JLL Vietnam, the market still possesses substantial growth potential.
JLL estimates that even if only a small percentage of manufacturers across the Asia-Pacific region decide to expand or relocate operations to Vietnam, current industrial supply could be fully absorbed.
The key challenge today is no longer attracting investment, but rather attracting high-quality projects in priority sectors that utilize advanced technology, support environmental sustainability, and align with Vietnam’s long-term development goals.
Will Tran emphasized that ESG criteria are becoming increasingly important in both investment and leasing decisions.
Companies operating in:
- Electronics
- High-tech manufacturing
- Data centers
- Logistics
are increasingly prioritizing projects that offer energy efficiency, renewable energy integration, and support carbon reduction targets.
This trend is expected to accelerate the development of:
- Green industrial parks
- Modern factories
- Next-generation logistics facilities
over the coming years.
Vietnam Remains Competitive Despite Rising Costs
Although Vietnam is no longer viewed solely as a low-cost manufacturing destination, the country continues to maintain strong competitiveness through:
- Its strategic geographic location
- Attractive investment policies
- Ongoing infrastructure development
- Continuous improvements in workforce quality through education and skills training
These advantages are expected to position Vietnam as a leading destination for high-tech manufacturing and value-added industries in the years ahead.
Conclusion
Vietnam’s industrial real estate sector continues to prove itself as the “golden goose” of the property market. Strong FDI inflows, expanding manufacturing activities, and the rise of green industrial development are creating a solid foundation for long-term growth. With favorable market fundamentals and increasing demand from global investors, industrial real estate is expected to remain one of Vietnam’s most attractive investment sectors through 2026 and beyond.
References:
Free access to exclusive information on warehouse, factory, and land rentals in Dong Nai, Binh Duong, Long An, Ho Chi Minh City, and more.
KHU CÔNG NGHIỆP 247 is a company operating in the field of buying, selling, and leasing factories and real estate.. We are proud to be a leading provider of real estate services in Vietnam. We have a team of highly qualified and experienced real estate consultants who always place trust and credibility at the core of everything we do.
Phone: 0901 490 348
Email: datkhucongnghiep247@gmail.com
Website: datkhucongnghiep247.com.vn